The Claim That Took Three Weeks and Should Have Taken Three Days A policyholder submits a health insurance claim with a hospital discharge summary, medical bills, and diagnostic reports. The documents are scanned, slightly rotated, and partially in a regional language. They arrive in a shared inbox. A claims processor downloads them, opens each one, and manually keys the details into the claims system: patient name, admission date, diagnosis, procedure codes, line-item charges. The processor is experienced but overloaded. The claim sits in a queue for four days before it is touched. Then it goes to a medical reviewer, who spends another hour verifying that the procedure matches the diagnosis and the charges match the policy terms. By the time the claim is settled, three weeks have passed. The policyholder has called support four times.
This is the operational reality of insurance claims in India—and it is where AI-powered claims processing delivers its value. Not by replacing the claims processor or the medical reviewer, but by removing the manual extraction, the queue delays, and the repetitive verification that consume time without adding judgment.
Indian insurers have moved from pilots to production. Quantiphi deployed an intelligent document processing solution for a leading general insurer that achieved 98.7% classification accuracy and 96.8% extraction accuracy, cutting manual effort by 50% and reducing quote generation to under three minutes . Newgen helped a life insurer achieve 35% faster claim settlement and 15% fewer underwriting discrepancies . HDFC ERGO integrated AI models to analyze medical bills, discharge summaries, and vehicle damage images, streamlining claims adjudication and risk assessment . Bajaj Allianz uses AI to approve claims within minutes for certain health products .
But the regulatory framework is still forming. IRDAI constituted a seven-member working group on AI governance in June 2026, with a three-month deadline to propose a framework for ethical, transparent, and explainable AI use, with specific attention to claims processing and fraud detection—the two functions where automated decision-making carries the greatest regulatory exposure . The DPDP Act is expected to come into force by May 2027, with sector-specific compliance requirements for insurers anticipated .
This guide is written for Indian insurers, TPAs, InsurTech founders, and claims leaders evaluating AI-powered processing. We will cover the document AI, the verification and fraud detection, the risk assessment, the IRDAI governance context, real costs in rupees and dollars, DPDPA compliance, and a phased implementation framework with clear go/no-go gates.
The Claims Processing Pipeline: Where AI Fits
A claims process has distinct stages, each with different automation potential.
Stage 1: Claim Intake and Document Ingestion
Claims arrive through multiple channels: email attachments, portal uploads, mobile app photos, WhatsApp images, and physical documents. The first challenge is ingesting them all and identifying what they are.
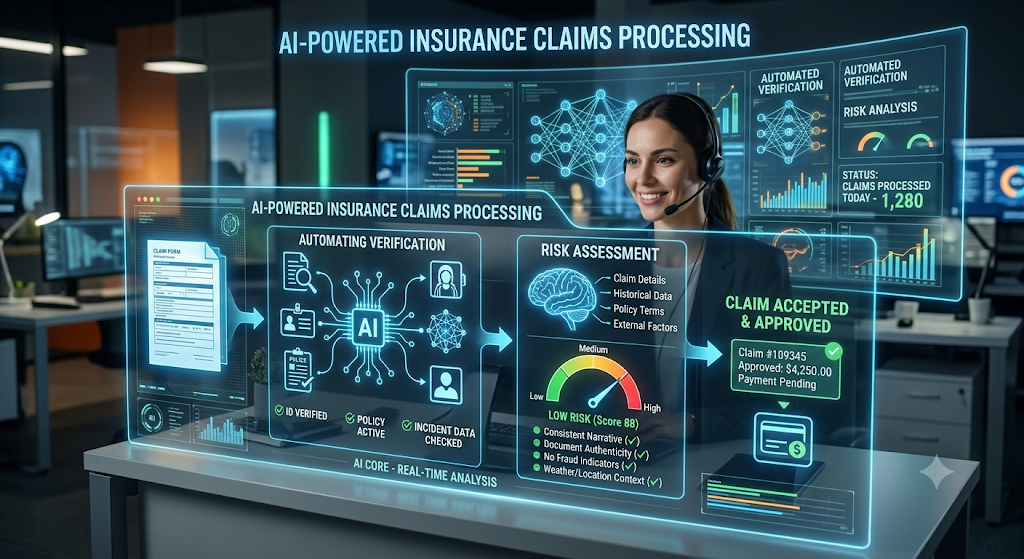
AI classifies documents: medical certificate, hospital bill, discharge summary, pharmacy receipt, diagnostic report, motor damage photo, FIR, policy document. Quantiphi's solution monitors email inboxes to ingest broker and client documents automatically, classifying them with 98.7% accuracy . Quantum AI's llodi platform classifies various claim documents including medical certificates, receipts, and detailed medical expense statements .
Stage 2: Data Extraction
Once classified, the documents must be read. AI extracts key fields: patient name, policy number, admission and discharge dates, diagnosis codes, procedure codes, line-item charges, hospital name, and treating doctor.
The extraction challenge in India is specific: documents may be scanned at poor quality, rotated, or partially in regional languages. Quantum AI developed its own document recognition technology using overlapping segmentation—dividing documents into multiple overlapping areas for reading—to recognize documents with high accuracy even when text is broken, overlapped, or rotated .
Stage 3: Pre-Verification and Policy Checking
Before a claim can be assessed, it must be verified against the policy: Is the policy active? Does the diagnosis fall within the covered scope? Is the hospital in the network? Are the charges within the policy limits?
AI links claim data to policy terms and checks the basic eligibility. Quantum AI's llodi links accident and contract pre-verification, organizing materials needed for review and recording the basis for each AI decision so reviewers can check the policy terms applied .
Stage 4: Risk Assessment and Fraud Detection
This is where AI adds the most value—and carries the most risk.
Risk assessment evaluates the likelihood that a claim is valid and the amount is appropriate. AI models can analyze patterns: Is the diagnosis consistent with the procedure? Are the charges within the normal range for that hospital and procedure? Is the length of stay plausible?
Fraud detection flags claims that exhibit patterns associated with fraud: claim timing (immediately after policy inception), frequency (multiple claims in a short period), provider patterns (hospitals with unusually high claim rates), and document anomalies (inconsistent fonts, altered amounts).
The critical caveat: a fraud flag is not evidence of fraud. As Indian consumer law analysis notes, an insurer cannot reject a claim simply because an AI flagged it as suspicious. They must conduct an actual investigation and find specific evidence . The AI narrows the investigation; it does not replace it.
Stage 5: Review and Settlement
The final decision remains with a human—a claims processor, a medical reviewer, or a claims committee. AI prepares the case, presents the extracted data, flags the risks, and calculates the benefit. The human reviews and decides.
IRDAI's Master Circular on Health Insurance requires that no claim may be repudiated without the approval of a Claims Review Committee, which independently decides on every repudiation . If AI has been used in a claim that ends in repudiation, the committee should know what the AI contributed—a question that Indian insurers have not publicly addressed .
The Pipeline Table
| Stage | AI Role | Human Role |
|---|---|---|
| Intake | Classification, channel ingestion | Exception handling |
| Extraction | Field extraction, structuring | Verification of low-confidence fields |
| Pre-verification | Policy eligibility check | Edge case review |
| Risk/Fraud | Pattern detection, anomaly flags | Investigation, final determination |
| Settlement | Benefit calculation, draft | Final decision, repudiation approval |
For teams building the claims AI and document pipelines, our AI Development and AI Automation practices cover the full stack.
The IRDAI Governance Context: What Insurers Must Prepare For
The regulatory framework for AI in Indian insurance is evolving rapidly. Insurers that build now must anticipate what is coming.
The IRDAI Working Group (June 2026)
IRDAI formed a seven-member working group on AI governance in June 2026, chaired by Sandeep K. Shukla of IIIT Hyderabad, with members from CERT-In, RBIH, and insurers. The mandate includes :
Mapping current AI adoption among regulated entities.
Proposing a framework for ethical, transparent, and explainable AI, with specific attention to claims processing and fraud detection.
Prescribing security controls to mitigate risks from AI-driven automated attacks.
Developing an audit framework covering pre-deployment and post-deployment requirements.
Assessing skills gaps and capacity-building needs.
The audit framework is the mechanism through which accountability for AI errors will be established—covering what happens before an AI system goes live and how it is monitored afterward .
IRDAI's April 2026 Cyber Security Guidelines
IRDAI issued revised information and cyber security guidelines in April 2026, directing regulated entities to begin compliance in the current financial year. The AI working group extends this into the ethical and governance dimensions of automated decision-making .
The Consumer Rights Context
IRDAI mandates that AI systems used in underwriting must be validated for accuracy and fairness. Claims decisions must comply with policy terms—AI cannot deny valid claims by misapplying fraud scores. Customers have the right to know the basis of decisions affecting their policy. Insurers are responsible for the outputs of AI systems they deploy .
The Compliance Table
| Requirement | Source | Implication |
|---|---|---|
| AI validated for accuracy/fairness | IRDAI | Testing, bias audits |
| Claims decisions comply with policy | IRDAI | AI cannot override terms |
| Right to know basis of decision | IRDAI | Explainability |
| Insurer responsible for AI outputs | IRDAI | Cannot blame the AI |
| Claims Review Committee for repudiation | Master Circular | Human decision on rejection |
| Audit framework | Working Group (pending) | Pre/post deployment audits |
Real Costs in India (2026)
AI claims processing costs depend on the scope: document extraction only, or full pipeline with fraud detection and risk assessment.
Implementation Costs
| Scope | Cost (₹) | Cost ($ approx.) | Timeline |
|---|---|---|---|
| Document extraction (classification, extraction) | ₹8–20 lakh | $9,600–$24,000 | 10–16 weeks |
| Extraction + pre-verification | ₹15–35 lakh | $18,000–$42,000 | 16–24 weeks |
| Full pipeline (extraction, fraud, risk, workflow) | ₹35–80 lakh | $42,000–$96,000 | 24–36 weeks |
| Enterprise platform (multi-line, integrations, governance) | ₹80 lakh–₹2 crore+ | $96,000–$2,40,000+ | 36–52 weeks |
Note: USD conversions at ₹83/$. Ranges are indicative for Indian insurers and TPAs.
Running Costs
| Component | Monthly Cost (₹) | Monthly Cost ($ approx.) | Notes |
|---|---|---|---|
| Document AI/OCR | ₹20,000–₹1,50,000 | $240–$1,800 | Per-document pricing |
| LLM/ML inference | ₹15,000–₹1,00,000 | $180–$1,200 | Fraud detection, risk scoring |
| Hosting | ₹20,000–₹1,00,000 | $240–$1,200 | Indian region for data localisation |
| Maintenance | 15–25% of build annually | — | Model updates, compliance |
The ROI Case
For an insurer processing 50,000 claims per month:
Manual processing time: 15 minutes per claim = 12,500 hours/month.
Time saved with AI extraction: 60% = 7,500 hours/month.
Cost saving: 7,500 hours × ₹400/hour = ₹30 lakh/month.
Annual saving: ₹3.6 crore.
Payback: 2–6 months on a ₹35–80 lakh implementation.
Plus, faster settlement improves customer satisfaction and reduces support calls.
India-Specific Compliance: DPDPA and Data Localisation
DPDPA and Claims Data
Claims data is among the most sensitive personal data: medical records, diagnoses, treatment history, financial details. The DPDP Act is expected to come into force by May 2027, with insurance-specific requirements anticipated .
Key obligations:
Consent: policyholders must consent to their data being used for claims processing.
Purpose limitation: claims data should not be repurposed.
Data minimisation: extract only what is needed for the claim.
Access control: claims data should only be accessible to authorized personnel.
Retention: define retention periods for claims records.
Breach notification: notify CERT-In within six hours and affected individuals.
The Health Insurance Compliance Burden
Health insurance players face the highest compliance burden because of the sensitivity of medical information and the involvement of multiple entities—hospitals, TPAs, diagnostic firms, and technology vendors . Insurers may need tighter norms on consent management, restrictions on sharing policyholder data with intermediaries, and stricter accountability for outsourcing partners .
Data Localisation
For regulated sectors, claims data and AI processing may need to stay in India. Choose Indian cloud regions for hosting and processing.
The Compliance Checklist
| Requirement | Implementation | Priority |
|---|---|---|
| Consent | At policy issuance and claim | High |
| Purpose limitation | Claims-only use | High |
| Access control | Role-based access to claims | High |
| Retention | Policy-defined periods | High |
| Data localisation | Indian region | High (regulated) |
| Breach notification | Incident response | High |
| TPA/vendor DPAs | Contracts with all processors | High |
Implementation Framework: A Phased Approach With Cost Gates
Phase 1: Claims Process Audit (Week 1–3)
Objective: Understand current claims flow, volumes, and pain points.
Activities:
Map the claims process: intake, extraction, verification, review, settlement.
Measure current processing time and error rates.
Identify document types and volumes.
Assess compliance requirements (IRDAI, DPDPA).
Define success metrics.
Cost: ₹1–3 lakh ($1,200–$3,600).
Go/No-Go: Process mapped. Business case validated.
Phase 2: Document Extraction (Week 4–14)
Objective: Automate document classification and extraction.
Activities:
Implement document ingestion.
Implement classification.
Implement extraction with confidence scoring.
Build review interface for low-confidence extractions.
Test on real claim documents.
Cost: ₹8–20 lakh ($9,600–$24,000).
Go/No-Go: Extraction accuracy >95% on key fields. Review queue manageable.
Phase 3: Pre-Verification and Risk (Week 15–26)
Objective: Automate policy checking and risk scoring.
Activities:
Integrate policy data.
Implement eligibility checks.
Implement risk scoring.
Implement fraud detection flags.
Build review workflow.
Cost: ₹15–35 lakh ($18,000–$42,000).
Go/No-Go: Verification works. Risk flags accurate.
Phase 4: Governance and Scale (Week 27–38)
Objective: Add audit, explainability, and scale.
Activities:
Implement audit logging.
Implement decision explainability.
Implement human-in-the-loop for repudiation.
Scale to production volume.
Train claims team.
Cost: ₹15–40 lakh ($18,000–$48,000).
Go/No-Go: Governance review passes. Production stable.
Phase Summary Table
| Phase | Duration | Key Deliverable | Cost (₹) | Go/No-Go Criteria |
|---|---|---|---|---|
| 1. Audit | 3 weeks | Process map, metrics | 1–3 lakh | Business case |
| 2. Extraction | 11 weeks | Document AI | 8–20 lakh | Accuracy >95% |
| 3. Verification | 12 weeks | Policy checks, risk | 15–35 lakh | Flags accurate |
| 4. Governance | 12 weeks | Audit, explainability | 15–40 lakh | Review passes |
Risks, Pitfalls, and Governance
The Most Common Claims AI Failures
Over-reliance on AI for rejection. AI flags a claim as fraudulent, and it is rejected without investigation. Mitigation: Human investigation before rejection, Claims Review Committee.
Extraction errors on poor documents. Scanned, rotated, or regional-language documents fail. Mitigation: Confidence scoring, human review.
Bias in risk scoring. The model replicates historical biases. Mitigation: Bias audits, fairness testing.
No explainability. The insurer cannot explain why a claim was denied. Mitigation: Decision logging, explainable AI.
DPDPA gaps. Claims data processed without consent or with inadequate security. Mitigation: Consent, access control, DPAs.
Regulatory uncertainty. IRDAI's framework is still forming. Mitigation: Build to the emerging standard, document decisions.
Risk Summary Table
| Risk | Likelihood | Impact | Mitigation |
|---|---|---|---|
| AI rejection without investigation | High | Critical (regulatory) | Human investigation |
| Extraction errors | High | High | Confidence, review |
| Bias in scoring | Medium | High (fairness) | Bias audits |
| No explainability | High | High (IRDAI) | Decision logging |
| DPDPA gaps | Medium | Critical | Consent, access |
| Regulatory uncertainty | High | Medium | Document decisions |
Benchmark Summary and Decision Framework
Decision Matrix: Build vs Buy
| Your Situation | Recommended Path |
|---|---|
| Standard claims, single line | Buy IDP + configure |
| Multi-line, custom workflow | Build custom |
| Unique fraud models | Build custom |
| Early stage | Buy IDP, build later |
Claims Priority Table
| Priority | Capability | Why |
|---|---|---|
| 1 | Document extraction | Fastest ROI |
| 2 | Human review workflow | Prevents AI errors |
| 3 | Policy verification | Accuracy |
| 4 | Fraud detection | Cost saving |
| 5 | Audit/explainability | Regulatory |
The One-Paragraph Decision Rule
If you are automating claims, start with document extraction—it delivers the fastest ROI. Build the human review workflow before you build the fraud detection. Keep the final decision with a human, especially for repudiation. Implement audit logging and explainability from day one, because IRDAI's framework will require it. And ensure DPDPA compliance—consent, access control, retention—before the Act comes into force in 2027.
Frequently Asked Questions
1. How much does AI claims processing cost in India?
Document extraction costs ₹8–20 lakh ($9,600–$24,000). Full pipeline with fraud and risk costs ₹35–80 lakh ($42,000–$96,000). Enterprise platform costs ₹80 lakh–₹2 crore+.
2. What accuracy can AI achieve in claims document extraction?
Leading implementations report 98.7% classification accuracy and 96.8% extraction accuracy .
3. Can AI reject a claim?
No. IRDAI requires that no claim may be repudiated without the approval of a Claims Review Committee. AI can flag and prepare, but the decision remains with humans .
4. How does IRDAI regulate AI in insurance?
IRDAI formed a working group in June 2026 to develop an AI governance framework, with specific attention to claims processing and fraud detection . The framework is expected to include audit requirements.
5. What is the difference between AI risk assessment and AI fraud detection? Risk assessment evaluates the likelihood that a claim is valid and the amount is appropriate. Fraud detection flags patterns associated with fraud. Both require human investigation before action.
6. How does DPDPA affect claims processing?
Claims data is sensitive personal data. Consent, purpose limitation, data minimisation, access control, and retention apply. The Act is expected to come into force by May 2027 .
7. What document types can AI extract?
Medical certificates, hospital bills, discharge summaries, pharmacy receipts, diagnostic reports, motor damage photos, and FIRs. Accuracy varies by document quality.
8. How long does implementation take?
Document extraction takes 10–16 weeks. Full pipeline takes 24–36 weeks. Timeline depends on document types and integrations.
9. Should I build or buy claims AI?
Buy IDP for standard extraction. Build custom for multi-line workflows and unique fraud models.
10. What is the biggest risk in claims AI?
Over-reliance on AI for rejection. AI flags are not evidence of fraud. Human investigation is required.
11. How do I ensure AI fairness in claims?
Conduct bias audits, test on diverse claim populations, and implement human review for consequential decisions.
12. How can Innovative AI Solutions help?
Innovative AI Solutions builds AI-powered claims processing for Indian insurers and TPAs—document extraction, policy verification, fraud detection, risk scoring, human-in-the-loop workflows, and DPDPA-compliant data handling. Our Delhi-based team handles assessment, implementation, and governance. Visit https://innovativeais.com to discuss your requirements.
Contact Innovative AI Solutions
Ready to process claims faster without sacrificing accuracy or compliance?
[One-line supporting sentence.]
Contact Information
Innovative AI Solutions
📍 Netaji Subhash Place, Pitampura, Delhi – 110034
🌐 Website: https://innovativeaislabs.com 📧 Email: info@innovativeais.com
📞 Phone: +91 7464 099 059 / +91 96899 67356
Business Services
AI Automation
AI Development
AI Consulting
Machine Learning Solutions
Deep Learning Solutions
Generative AI Services
NLP Solutions
AI Agents
AI Chatbots
Voice AI
CRM Development
Custom Software Development
Website Development
Mobile App Development
About the Author
Abhishek Kumar
Founder & CEO, Innovative AI Solutions
5+ years building production AI systems for Indian businesses. Based in Delhi, serving clients across India.
Ready to build AI solutions for your business?
Innovative AI Solutions — Delhi's leading AI development company. Free consultation available.
Get Free Consultation →
A practical 2026 guide for Indian insurers and TPAs automating claims—document extraction, fraud detection, risk scoring, IRDAI governance, real rupee costs, and DPDPA-compliant data handling.
#AIInsuranceClaims #ClaimsProcessing #InsuranceAutomation #DocumentExtraction #FraudDetection #RiskAssessment #IRDAI #DPDPA #MeitY #HealthInsuranceAI #MotorClaimsAI #ClaimsVerification #InsuranceTechnology #DelhiNCR #InnovativeAISolutions
Copyright ©️ 2015–2026 Innovative AI Solutions. All Rights Reserved. | Privacy Policy | Terms & Conditions